Learn To Trade Forex • Best Forex Trading Course • AsiaForexMentor

 English
 简体中文
 繁體中文
 日本語
 한국어
 Bahasa Melayu
 Bahasa Indonesia
 Filipino
 ไทย
 Tiếng Việt
 हिन्दी
 العربية
 Italiano
 Português
 Русский
 Español
 Français
- Best Forex BrokersRaw spreads, ECN execution and regulation — tested on live accounts.Best Stock BrokersCommissions, market access and platform depth, compared.Best Prop FirmsFunding rules, drawdown limits and real payout records.Best Crypto BrokersFees, custody and coin coverage across the major exchanges.AFM Top Pick
Every other site ranks ten brokers. We rank one — and show you exactly why.
See the #1 pick → - Articles
- Awards
- Events
- Newsletter
 Singapore
 Cambodia
 Myanmar
 Brunei
 Australia
 New Zealand
 Switzerland
 UAE
 United States
 Mexico
 Argentina
 South Africa
 IC Markets
 Pepperstone
 AvaTrade
 XM
 Plus500
 RoboForex
 TMGM
 Exness
 JustMarkets
 Orbex
 Interactive Brokers
 Saxo
 Tiger Brokers
 Binance
 Coinbase
 Gemini Exchange
 Kraken
 iFunds
 IC Funded
 The 5%ers
 TopStep
 IQ Option
 Pocket Option
 RaceOption
 IQCent

iFunds Review 2026
iFunds removes the two things traders most dislike about prop firms: there is no mandatory challenge, and there is no profit target to hit before you can withdraw. You pay a participation fee, you get an account, and anything over $50 can be taken out at any time – with a promise to process it within 24 hours or add 10%. That is a genuinely trader-friendly structure. What it costs you is the split. iFunds keeps 50% of your profits on all three published tiers, where FTMO pays 80-90% and TopStep 90%. Add a participation fee worth 7-10% of the account size and the economics only work if you are consistently profitable at a level most traders never reach. It is also worth being clear that iFunds holds no financial licence – a Saint Lucia company registration is not regulation.
Risk warning: your capital is at risk. Forex and CFDs carry the potential for gains, but statistically only 11–25% of traders profit while 74–89% lose their investment. AFM earns a commission if you open an account through our links — it never changes how we score a broker.
- No challenge – funding is instant once the fee is paid
- No profit target before you can withdraw
- Withdraw anything over $50 at any time, no waiting period
- Payout in 24 hours or iFunds adds 10%, up to $1,000
- Static drawdown measured on the initial balance, not trailing
- Only one rule to break – maximum drawdown
- Low entry point at $250 for a $2,500 account
- 50% profit split – roughly half the industry standard
- Fee is 7-10% of the account size, higher than most rivals
- No financial licence – Saint Lucia and Cyprus registrations only
- Account sizes top out at $10,000 on the published tiers
- The fee is spent, not deposited – it is never returned
- Whether accounts are live or simulated is not stated
- No published daily loss limit to plan around
- Every headline figure — minimum deposit, spreads, commission, leverage and fees — was read off iFunds’s own current published documents, not copied from another review site.
- Each licence claim was checked against the regulator’s own public register. Regulators named on the operator’s marketing but absent from the register are not printed here.
- Treated this as an evaluation product, not a brokerage: the fee is a fee, not a deposit, the firm holds no financial licence, and the payout depends on rules the firm can change.
- Scored out of 10 on the AFM Trust Score — regulation, real all-in cost, platform, market access and withdrawal experience. Commercial relationships carry no weight in the score.
- Anything we could not confirm from a primary source was left out rather than estimated. Figures move; re-check before you deposit.
Last verified September 2026. iFunds can change its pricing, leverage and entity terms at any time — confirm the current figures on its own site before you open an account. Spotted something out of date? Tell us.
Ezekiel has traded foreign exchange for over two decades and built the One Core Program, the trading curriculum Asia Forex Mentor teaches to retail and institutional traders across Asia. He sets the scoring criteria these broker reviews are graded against.
On this page
iFunds Review: the short version
iFunds sells instant funding. There is no challenge to pass, no profit target to reach, and no minimum trading days. You pay a participation fee, an account is opened, and you can withdraw anything above $50 at any time. iFunds promises to process a payout within 24 hours or pay you 10% extra, up to $1,000.
For a trader who has failed challenges at other firms on a technicality, that is an appealing structure, and the single-rule design – only a 10% static maximum drawdown – is genuinely simpler than most.
Two numbers decide whether it is worth it. The profit split is 50%, where FTMO pays 80-90% and TopStep 90%. And the fee is 7-10% of the account size – $250 for a $2,500 account, $700 for $10,000. You are buying a smaller share of the upside at a higher entry cost than the established firms charge.
What is iFunds?
iFunds is a proprietary trading firm – a prop firm. It does not take deposits, hold client money or execute trades for the public. You are buying an evaluation product, not opening a brokerage account.
The distinction matters more than it sounds. At a broker, your deposit is your money and regulation exists to keep it that way. At a prop firm, the fee is a purchase. iFunds states this itself: “This amount is a program participation fee, not a deposit.” Once paid, it is spent.
What makes iFunds unusual within that category is that it skips the evaluation. Most prop firms sell a challenge: hit a profit target inside a drawdown limit and you get funded. iFunds funds you immediately and says the challenge route is optional. If you have watched a challenge fail on a daily-loss breach while you were up overall, you can see the appeal.
Is iFunds regulated? No – and here is what that means
iFunds names two companies:
- iFunds Ltd, registered in Saint Lucia, Registration No. 2024-00154.
- Synerjic Ltd, registered in Cyprus, Registration No. 474148.
Both of those are company registrations. Neither is a financial licence. A Cyprus registration number is not CySEC authorisation, and a Saint Lucia IBC registration is not regulation by anybody. iFunds holds no financial licence, is supervised by no financial regulator, and there is no compensation scheme, ombudsman or statutory dispute route behind it.
That is not a scandal – it is normal for the prop-firm sector, and it applies equally to FTMO, The5ers and IC Funded. Prop firms are not brokers, so they are not regulated as brokers.
What it means practically: your only protection is the firm’s own rules and its willingness to honour them. If iFunds declines a payout, changes its terms or stops trading, there is no regulator to appeal to. Judge the firm on its track record and its incentives, and never send money you cannot afford to lose outright.
iFunds accounts, fees and the 50% split
Three published tiers, all with the same rules and the same split:
Intern – $2,500 account, $250 fee. Starter – $5,000 account, $400 fee. Ambitious – $10,000 account, $700 fee. All three: 10% maximum drawdown, static, calculated on the initial balance. No profit target. 50% profit split.
Two things stand out when you put those numbers next to the rest of the market.
The fee is high relative to the account. $250 buys $2,500 of buying power – 10%. $700 buys $10,000 – 7%. By comparison, TopStep charges $49 a month for $50,000 of buying power, roughly 0.1% of the account per month.
The split is half the market rate. 50% is the number to focus on. If you make $1,000, you keep $500. At FTMO you would keep $800-900; at TopStep, $900. On a $10,000 account you have paid $700 up front for the right to keep half of what you earn.
iFunds mentions a higher split – up to 80% – at levels beyond these tiers. We could not verify that as a published product, so this review does not price it in. Ask before you buy if that is the basis on which you are buying.
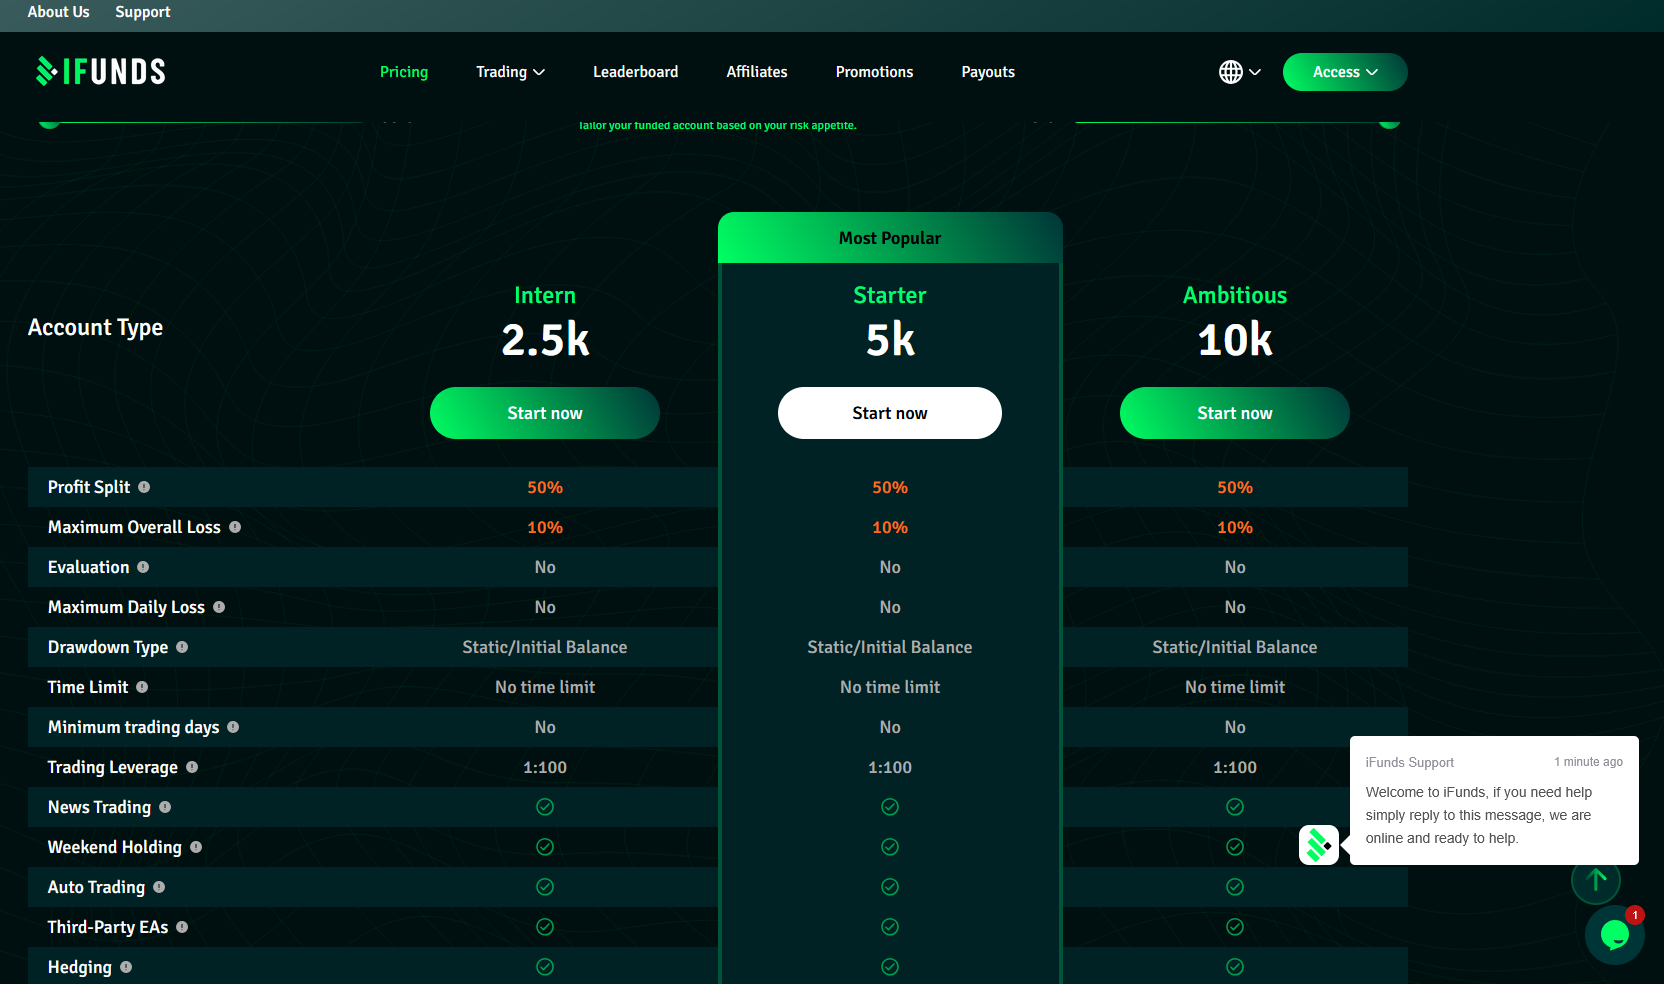
| Intern | Starter | Ambitious | |
|---|---|---|---|
| Account size | $2,500 | $5,000 | $10,000 |
| Participation fee | $250 | $400 | $700 |
| Fee as % of account | 10% | 8% | 7% |
| Profit split | 50% | 50% | 50% |
| Maximum drawdown | 10% static | 10% static | 10% static |
| Profit target | None | None | None |
| Minimum withdrawal | $50 | $50 | $50 |
The rules: one limit, and it is a good one
iFunds says only maximum drawdown applies, capped at 10% and calculated statically on the initial balance.
That static calculation is genuinely favourable and worth understanding, because it is where most traders lose challenges elsewhere. A static drawdown on a $10,000 account means your floor is $9,000 and stays $9,000 – if you trade up to $12,000 and back down to $9,500, you are fine. A trailing drawdown follows your high-water mark upwards: reach $12,000 and your floor rises to $11,000, so falling to $9,500 breaches it even though you are still up $500 overall.
iFunds uses the friendlier version, and combined with no profit target and no minimum trading days it produces an unusually clean rule set. This is the strongest thing about the product and the reason it is not scored lower.
The absence of a published daily loss limit cuts both ways – nothing to breach accidentally, but also no guardrail against a single catastrophic session.
Payouts
This is iFunds’ other genuine strength. There is no profit target gating withdrawals, the minimum is $50, and there is no waiting period – profit above $50 can be withdrawn at any time.
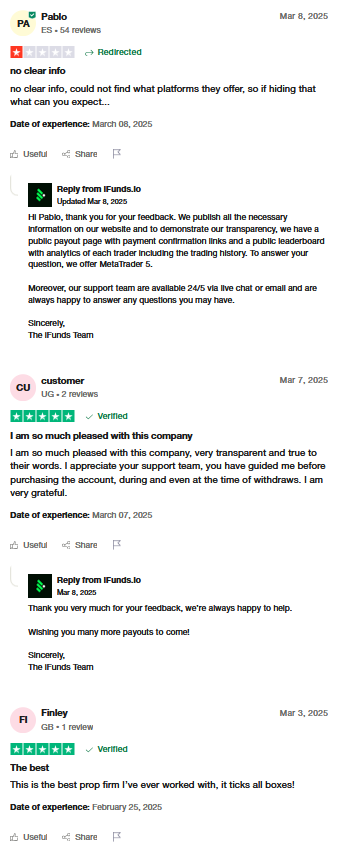
iFunds backs that with a guarantee: “process your payout within 24 hours, or we will pay you 10% extra, up to $1000”. Putting a penalty on its own slowness is a meaningful commitment, and slow or contested payouts are the most common complaint across this entire sector.
Bear in mind that the payout is 50% of profit. Fast access to half your gains is still fast access to half your gains.
Who iFunds suits
iFunds makes sense if you have repeatedly failed challenges on rule technicalities rather than on profitability; you want static rather than trailing drawdown; you want to withdraw small amounts frequently instead of waiting for a monthly cycle; or you want to start with a small, capped outlay.
Look elsewhere if the economics are what matter. A 50% split with a 7-10% entry fee is expensive. FTMO and TopStep both ask you to pass an evaluation, and both then pay you 80-90% instead of half.
And look elsewhere if you want any regulatory recourse – though on that point every prop firm is in the same position.
How iFunds compares
Against the established firms, iFunds trades economics for convenience. It is the easiest to get funded with and the least rewarding once you are.
FTMO requires a two-stage evaluation and pays 80-90%. TopStep requires a Combine and pays 90% on futures. The5ers also uses static drawdown – the feature iFunds leads with – while paying a far better split.
The honest summary: iFunds is competing on speed and simplicity, not on how much money you keep.
| iFunds | FTMO | TopStep | |
|---|---|---|---|
| Evaluation required | No – instant funding | Yes, two stages | Yes, Trading Combine |
| Profit split | 50% | 80-90% | 90% |
| Entry cost | $250 for $2,500 | Per-challenge fee | $49/mo for $50K |
| Drawdown type | 10% static | Max and daily loss | Trailing max loss |
| Profit target | None | 10% then 5% | $3,000 on $50K |
| Market | Not stated | Forex and CFDs | Futures only |
| Financial licence | None | None | Brokerage arm is NFA-registered |
Conclusion: is iFunds worth it?
iFunds scores 5.9. The product design is better than the score suggests – no challenge, no profit target, static drawdown, $50 withdrawals with a 24-hour guarantee. If prop-firm rules are what keep beating you, iFunds has removed most of them.
The score reflects what you pay for that. A 50% profit split is roughly half the market rate, and a participation fee of 7-10% of the account size is well above what the larger firms charge. You are paying more, up front, to keep less of what you make.
Buy iFunds for the rules if the rules are your problem. If your problem is making money consistently, a better split elsewhere will matter far more, and no prop firm – iFunds included – is a substitute for an edge.
- iFunds pricing – account tiers, fees and profit split — ifunds.io/pricing (checked September 2026)
- iFunds – programme terms and company registrations — ifunds.io (checked September 2026)
iFunds Review FAQs
Is iFunds regulated?
No. iFunds Ltd is a Saint Lucia company registration (2024-00154) and Synerjic Ltd a Cyprus company registration (474148). Neither is a financial licence, and no financial regulator supervises iFunds. That is normal for prop firms, but it means there is no compensation scheme or statutory dispute route if something goes wrong.
What is the iFunds profit split?
50% on all three published tiers – Intern, Starter and Ambitious. That is roughly half the industry standard: FTMO pays 80-90% and TopStep 90%. iFunds refers to a higher split at levels beyond these tiers, but we could not verify it as a published product.
Does iFunds have a challenge?
No. Funding is instant once you pay the participation fee, and iFunds states that taking its challenge is optional. There is also no profit target and no minimum number of trading days.
How much does iFunds cost?
$250 for a $2,500 account, $400 for $5,000 and $700 for $10,000. That is 7-10% of the account size, which is high for this sector. iFunds is explicit that the amount is a participation fee, not a deposit – it is spent, not held for you.
What is the iFunds drawdown rule?
A 10% maximum drawdown, calculated statically on your initial balance. Static means the floor does not move up as you profit – on a $10,000 account it stays at $9,000. That is more forgiving than a trailing drawdown, which rises with your high-water mark.
How fast are iFunds payouts?
iFunds guarantees processing within 24 hours or it pays 10% extra, up to $1,000. The minimum withdrawal is $50 and there is no waiting period, so profit above $50 can be taken at any time. Remember the payout is 50% of profit.
Is my money safe with iFunds?
The participation fee is not held for you – it is a purchase, and iFunds says so. There is no deposit to protect and no regulator overseeing the firm. Treat the fee as spent the moment you pay it, and never pay more than you can afford to lose outright.
The verdict on iFunds
iFunds removes the two things traders most dislike about prop firms: there is no mandatory challenge, and there is no profit target to hit before you can withdraw. You pay a participation fee, you get an account, and anything over $50 can be taken out at any time – with a promise to process it within 24 hours or add 10%. That is a genuinely trader-friendly structure. What it costs you is the split. iFunds keeps 50% of your profits on all three published tiers, where FTMO pays 80-90% and TopStep 90%. Add a participation fee worth 7-10% of the account size and the economics only work if you are consistently profitable at a level most traders never reach. It is also worth being clear that iFunds holds no financial licence – a Saint Lucia company registration is not regulation.